
ACCOUNT ROUNDING NEW QUOTE REQUESTS
Account Rounding New Clients: Quote the Whole Household on the First Call
Account rounding new clients means discovering and offering to quote other personal lines during the first conversation about a new request. A licensed producer asks every requester the same core household questions, and the requester chooses which lines to quote and which policies to buy.
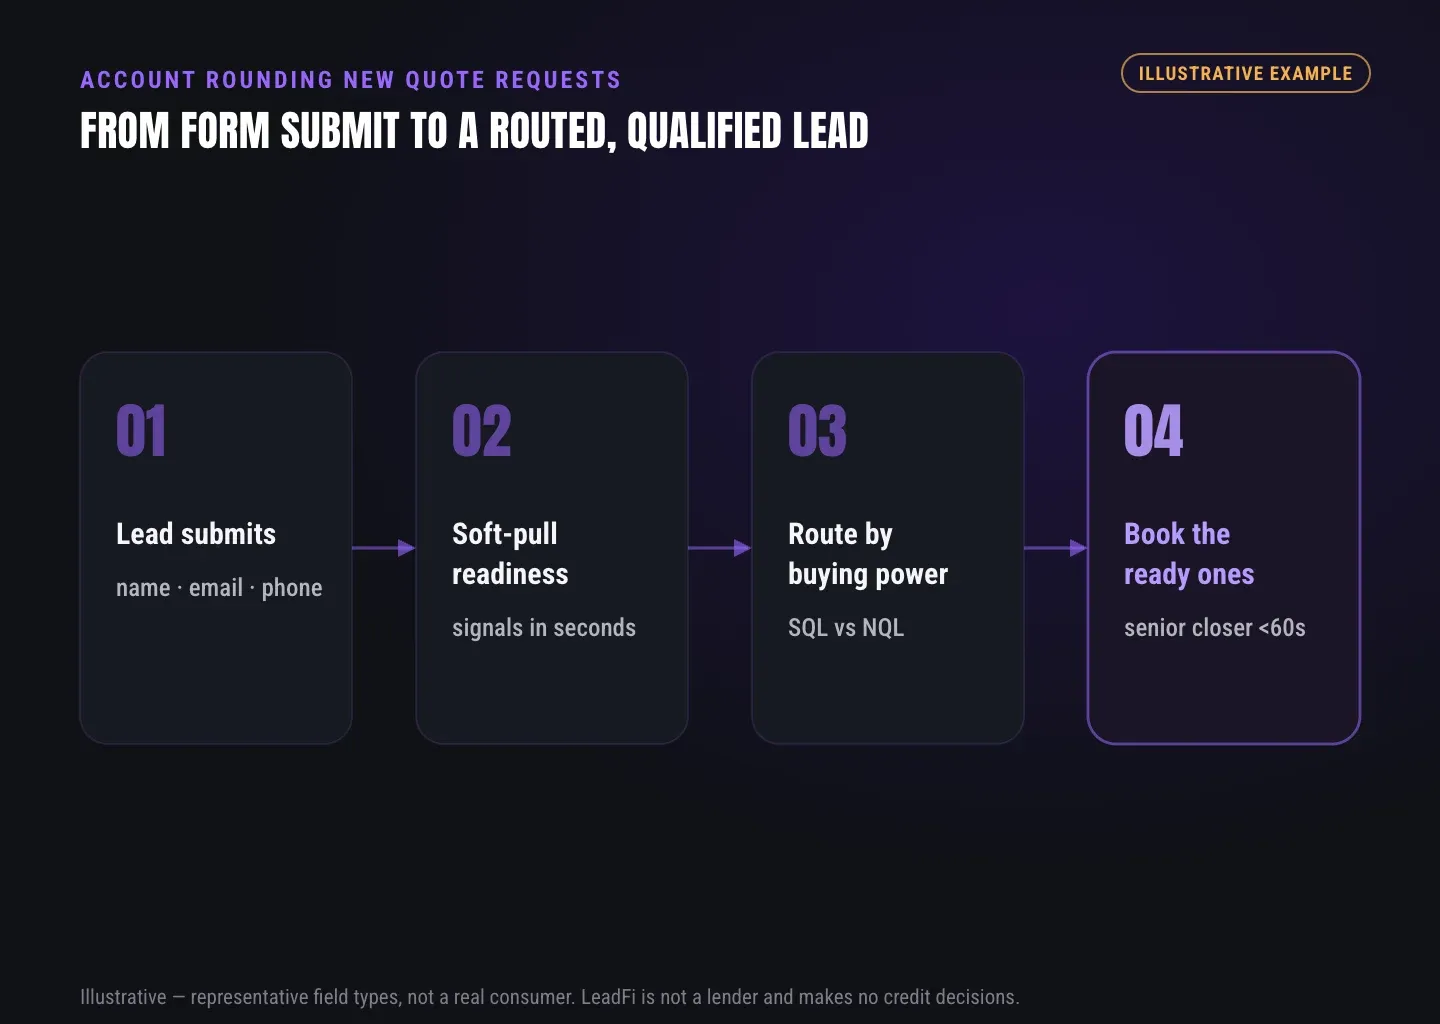
Watch a contact get pre-qualified.
This is exactly what your CRM gets back.
Your opt-in form
Soft pull · no impact to their credit
This is not a real soft pull. It's an example of the data points that land in your CRM contact record when a lead fills out your form.
LEADFI DEMO
Watch the demo, then start free or book a call.
PLATFORM OVERVIEW
What account rounding means on a brand-new request
Most account-rounding advice concerns households already in an agency’s book. Account rounding for a new client starts earlier: during the first conversation prompted by a new inbound quote request.
Start with the submitted request
The producer begins with the personal line named on the agency’s own form. The conversation then follows a standard order to discover whether the requester wants quotes for other personal lines.
An auto requester, for example, may also want to discuss renters, homeowners, recreational vehicle, or umbrella coverage. Each added line is an optional quote conversation, and the requester decides whether it moves forward.
Treat the first call as household discovery
The first call should establish which personal lines the requester wants reviewed. The producer uses a fixed question set rather than limiting the discussion to the originally requested line.
The conversation does not ask about a credit score, income, debt, budget, available credit, or ability to pay. Authorisation for the readiness read comes only through the agency’s own form—not through a scripted question on the call.
Offer every line consistently
The same household questions are asked, and the same personal lines are offered, on every first call regardless of band. The band says nothing about which households will buy more lines, select higher limits, or request an umbrella quote.
Both first-call routes reach the same carriers, products, and lines. The band does not change which household members, vehicles, residences, or other property the producer asks about.
Keep new-request and existing-client workflows separate
A new-request workflow begins with the agency’s own quote form and covers discovery and quoting during the first conversation. Existing-client account reviews use the agency’s separate service process.
Readiness routing applies only to the person who submitted the new form with its disclosures and authorisation. It is not extended to open quotes, past requests, current policyholders, or existing-client lists.
Record the requester’s choices
Each quoted line and the requester’s choice are recorded under the agency’s normal procedure; detailed documentation practices are outside this page’s scope.
For related operational reading, see a closer look at speed to lead for high ticket offers. The resource library also contains a closer look at final expense persistency early lapses, a separate subject outside this personal-lines workflow.
GUIDE
Household questions for every account rounding call
A consistent account-rounding process uses one household question set for every new requester. The readiness band never adds, removes, or reorders those questions.
Ask about vehicles and residences
After confirming the requested line, the producer asks whether the requester wants to discuss other personal vehicles. The producer also asks whether the primary residence is owned or rented and whether there are other residences the requester wants reviewed.
These questions may open conversations about auto, home, condo, renters, or other personal lines. Each carrier’s own rules determine what it will write.
Ask about other personal property
The producer can ask whether the requester wants quotes for motorcycles, boats, campers, or similar recreational vehicles. The question identifies an optional quote opportunity; it does not determine how another line is handled.
Ask neutrally about umbrella interest
Every requester may be asked whether they want to discuss an umbrella quote. The readiness band does not determine whether that question is asked or how strongly any coverage is recommended. No coverage choice is right for every household.
Avoid financial questions
The first-call script should not ask for scores, income, debts, budget, ability to pay, or details from a consumer report. It should not ask for call-time authorisation to access such information. The household discussion remains focused on the personal lines the requester wants quoted.
Use one fixed question order
A simple order is to confirm the requested line, ask about vehicles and residences, cover other personal property, ask about umbrella interest, and confirm which lines the requester wants quoted. The agency documents its own order and applies it to both first-call routes.
GUIDE
Quote each additional personal line on its own
Account rounding combines household discovery with separate quote choices. A requester may choose one, several, all, or none of the additional lines discussed.
Confirm interest before quoting
After the household questions, the producer repeats the lines the requester selected. This recap distinguishes general discovery from an instruction to prepare a quote.
For example, a requester may confirm interest in auto and renters quotes while passing on a recreational vehicle or umbrella discussion.
Keep the original request active
Answers about additional lines never remove or narrow the original quote request. Passing on another line does not alter the requester’s access to the requested quote or a full conversation with a licensed producer.
Present separate quote choices
Each personal line stands on its own. A requester can review multiple quotes without being required to purchase them together, and the agency follows each carrier’s terms and its own written procedure confirmed with counsel.
Leave pricing and coverage to the quote process
The readiness band does not set premiums, discounts, billing modes, down payments, payment plans, limits, deductibles, endorsements, or umbrella coverage. It is not entered into quoting, rating, underwriting, binding, or carrier workflows.
Licensed producers discuss available choices through the agency’s normal process. Carriers determine what they will write under their own rules.
Respect the requester’s decision
When a requester passes on an additional line, the producer moves on. The band is never used to reopen a declined discussion, pressure the requester, or make coverage or price promises.
See which of the leads you already have can actually afford to buy.
INTELLIGENCE LAYER
Where the readiness band sits in account rounding new clients
For account rounding new clients, the readiness band has one narrow function: deciding which licensed producer makes the first call. The agency’s written assignment rule defines the financially qualified route and the not financially qualified route.
Use SQL and NQL only as first-call routes
Some teams refer to the two paths as SQL and NQL routing. In this workflow, SQL maps to the financially qualified first-call route, while NQL maps to the not financially qualified first-call route.
Both producers are licensed and appointed with the same carriers for every line the household may need. They ask the same questions, offer the same personal lines, and provide the same access to a complete quote conversation. Neither route is a carrier, pricing, coverage, underwriting, insurability, or binding input.
Apply the same contact standard
Every request receives the agency’s same first-contact standard, and the band only selects the licensed producer who places the first call. It does not delay the first attempt.
The agency sets calls and messages through its own written contact policy, confirms that policy with counsel, and applies it consistently to every request.
Keep the band inside first-call assignment
Place the internal route as described in financial-readiness signals in your CRM, keeping it only in first-call assignment and never in a rater, carrier application, household record, rounding list, policy record, or outside-accessible portal.
The route is read only for the person who submitted the agency’s own form with its disclosures and authorisation. It is never read for a spouse, another driver, another household member, or a person named by the submitter.
Keep underlying financial information out of the workflow
People participating in this workflow see only the readiness band or route needed for assignment. They do not see, record, or repeat the underlying financial information to the requester.
The band is not analysed against quotes, binds, issued policies, carrier outcomes, claims, cancellations, retention, or other account results. Its role ends with first-call assignment.
For broader workflow context, review practical insights on financial readiness signals for sales teams.
Run existing-client reviews without a readiness read
Rounding campaigns and renewal reviews for existing clients run without any readiness read. Existing-client work follows the agency’s ordinary service and account-review process, separate from this new-request assignment workflow.
Support a compliance-aware launch
LeadFi can help teams plan form language, consent and disclosures, privacy language, and the internal handoff before launch. LeadFi supports compliance-aware workflows but does not provide legal advice or guarantee compliance. Clients should review their use case and written procedures with counsel.
Related reading: a closer look at speed to lead for high ticket offers, a closer look at final expense persistency early lapses, practical insights on financial readiness signals for sales teams.
| Household topic | Question asked on every first call |
|---|---|
| Requested line | “Let’s begin with the quote you requested. What would you like us to review?” |
| Vehicles | “Would you like to discuss any other personal vehicles?” |
| Primary residence | “Do you own or rent your primary residence?” |
| Other residences | “Are there other residences you would like us to discuss?” |
| Other property | “Do you have other personal property or recreational vehicles you want quoted?” |
| Umbrella interest | “Would you like to discuss an umbrella quote?” |
| Final review | “Which of these personal lines would you like us to quote?” |
Key takeaways
The short version
- Account rounding starts during the first conversation about a new request.
- Every requester receives the same household questions and personal-line options.
- SQL vs NQL changes only which equally appointed producer calls first.
- The readiness band stays solely inside first-call assignment.
- Existing-client rounding and renewal reviews run without a readiness read.
Quick answers
Fast answers before you dig in
What does account rounding new clients mean?
It means discovering and offering to quote other personal lines during the first conversation about a new inbound request while leaving each quote and purchase optional.
What does financially qualified mean in this workflow?
It means the request meets the agency’s written rule for assigning which licensed producer makes the first call. It says nothing about insurability, underwriting, premium, offered lines, quoting, or binding.
What does not financially qualified mean in this workflow?
It means a different licensed producer with the same carrier appointments makes the first call under the same contact standard and offers the same personal lines.
Does SQL vs NQL routing change the insurance quote?
No. In this workflow, SQL vs NQL routing changes only the internal first-call assignment. Questions, lines, carriers, quote access, and the contact standard remain the same.
Can the readiness band be used for existing-client account rounding?
No. Existing-client rounding campaigns and renewal reviews run without a readiness read.
FAQ
Common questions
What does account rounding new clients mean?
How is account rounding new clients different from existing-client rounding?
What household questions belong in a personal-lines account rounding call?
Can a readiness band determine which insurance lines are offered?
What does financially qualified mean for account rounding new clients?
What does not financially qualified mean here?
Does SQL vs NQL routing change account rounding new clients?
Sources
References
- CFPB — What is a credit inquiry? (hard vs. soft) (opens in a new tab)Federal regulator confirms a soft inquiry, unlike a hard inquiry, does not affect the consumer's credit score.
- VantageScore — VantageScore 4.0 credit scoring model (opens in a new tab)Official page describing VantageScore 4.0, the tri-bureau, trended-data model used to assess credit risk.
- CFPB — Who can request to see my credit report? (opens in a new tab)Federal regulator explains the FCRA rules governing who may obtain a credit report.
Know who is ready before your next sales call.
LeadFi can sit behind an agency’s own new quote form and return an internal readiness route for first-call assignment. Both routes retain the same contact standard, household questions, personal-line options, carrier access, and path to a full quote conversation.